Courier Fleet Insurance

ALDIUM Insurance

Aldium Insurance · Commercial Motor Specialists

Courier Fleet Insurance for Hire and Reward Operators

Every van on one policy with one renewal date, rated on your own claims record rather than each driver’s. Vehicles on and off as the work changes, driver age bands to suit how you recruit, and terms that stack up whether you run out of a country yard or a London depot.

  • One policy, one renewal date
  • Vans on and off mid-term
  • Any driver from 19, 21, 25 or 30+
  • Competitive UK-wide, rural or city
Tailored quotations

Get a Courier Fleet Insurance Quote

Tell us about the fleet and one of our commercial motor specialists will come back to you. Whether you run three vans on same-day work or forty on multi-drop, we approach insurers who write hire and reward risks and present the business properly — so the terms reflect how the fleet is actually run.

  • Independent brokers — we work for you
  • Motor and goods in transit together
  • Employed drivers and owner-drivers
  • No obligation at any stage

Prefer to talk it through?

0151 336 5881

Request your quote

A few details about the fleet and a commercial motor specialist will be in touch.

Your details are used only to prepare your quotation and are never sold on. Aldium Insurance Services Ltd is authorised and regulated by the Financial Conduct Authority (FCA No. 306687).

What is courier fleet insurance?

Courier fleet insurance puts every vehicle used for hire and reward work onto a single motor policy with one renewal date, one schedule and one set of documents. The fleet is rated on the operation’s own claims experience rather than on each driver’s individual history, the driver basis is set once across every vehicle, and vans can be added or removed during the year without starting again.

Hire and reward is the class of use that applies when a vehicle carries other people’s goods for payment. It is what separates courier work from a trades business carrying its own materials, and it narrows the field considerably — most personal and own-goods policies will not respond to a claim that happened on courier work, and most comparison sites will not quote it at all.

Why a fleet beats individual policies

The obvious saving is administrative: one renewal instead of six, one proposal instead of six, and one certificate to send a customer who asks for evidence of cover. The bigger difference is in how the risk is judged. On a fleet, the premium follows your record — so a new recruit with a thin licence history or one driver’s speeding conviction stops being a separate pricing event, and a well-run operation gets the benefit across every vehicle.

The practical one is flexibility. Courier fleets change constantly: routes are won and lost, vans are bought and written off, and drivers start at short notice. A fleet policy is built to absorb that through mid-term adjustments rather than a new policy each time — which is the subject of the next section.

Alongside the motor policy sits goods in transit cover for the consignments themselves, because the motor policy insures the van and not what is in the back. It is a separate contract doing a separate job, and it is covered further down the page.
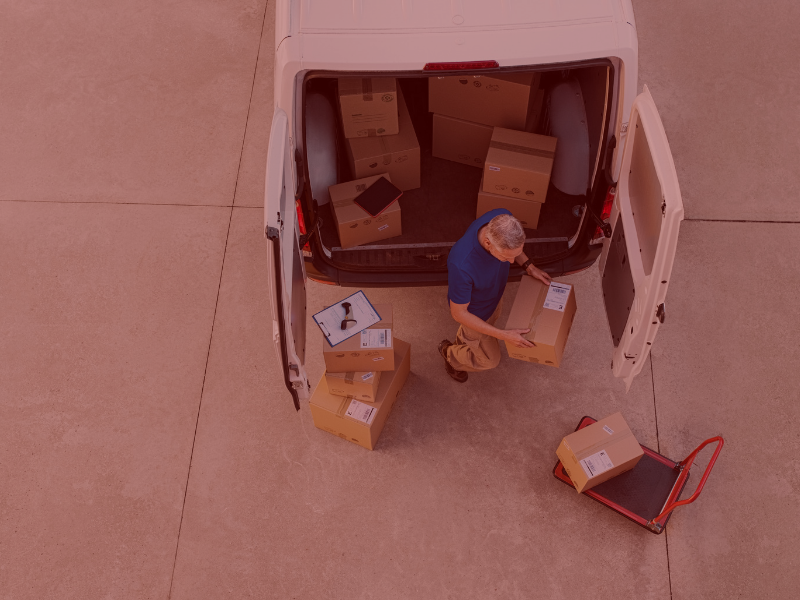
Courier loading parcels into the back of a van at a distribution depot
One policy, one renewal date, and a schedule that keeps up with the fleet.

What does courier fleet insurance cover?

The fleet motor policy does most of the work. These are the sections it is typically built from, plus the covers that usually sit alongside it:

  • Hire and reward motor fleet cover

    The core of the policy, and the bulk of the premium. Comprehensive, third party fire and theft or third party only across every vehicle on the schedule, written for carriage of goods for hire and reward — the class of use courier work needs and most van policies do not include.

  • Any driver, or a driver age band

    Fleet policies are commonly written on an any driver basis with a minimum age attached — typically any driver over 19, 21, 25 or 30. A lower band buys flexibility at a price; a higher one buys a cheaper premium and a smaller recruitment pool. Named-driver schedules are available where the team is settled.

  • Mid-term vehicle movements

    Vans added, removed, replaced or swapped during the policy year as an adjustment rather than a new contract. On a courier fleet this is used constantly, so what matters is not just that it is possible but how quickly it can be done — sometimes the same morning a vehicle arrives.

  • Windscreen, glass and fleet extras

    Windscreen and glass cover across the fleet, usually with its own excess and without affecting the no-claims position. Along with personal effects, sat-nav and keys and locks cover, these are the small-ticket sections a high-mileage courier fleet claims on most often.

Covers courier fleets often add

  • Uninsured loss recovery
  • Motor legal & prosecution defence
  • Trailers & swap bodies
  • Loading & unloading
  • Contingent liability for subcontractors
  • Hired-in vehicles
  • Gap insurance
  • Telematics & camera-rated terms
  • Temperature-controlled loads
  • High-value & attractive goods
  • European cover & CMR
  • Overnight security endorsements
  • Tools & equipment in transit
  • Directors & officers

One to watch — keep the schedule honest. Two things quietly invalidate courier fleet claims, and both are administrative. The first is a vehicle that never made it onto the schedule, or a replacement that was never swapped in. The second is class of use: if one van does own-goods work for another part of the business, or a driver uses one for social purposes at the weekend, that needs declaring rather than assuming. Neither takes long to put right, and both are a very poor thing to discover at the roadside. This page describes covers typically available to UK courier operators and is general information, not advice on your own circumstances; all policies are subject to their own terms, conditions, limits, excesses and exclusions.

A policy built to move as the fleet does

Courier operations change faster than almost any other kind of fleet. Routes come and go, vans arrive and leave, and drivers start on a Monday. The point of a fleet policy is that none of that should require a phone call to an underwriter and a fortnight’s wait.

  • Vehicles on and off mid-term

    A courier fleet is never the same size twice. Vans get bought, written off, sold, swapped and hired in, and the schedule has to keep up. On a fleet policy that is a mid-term adjustment rather than a new policy — no fresh proposal form, no second renewal date to remember, and the premium adjusted pro rata.

  • A driver basis that fits the operation

    Fleet policies are usually written on an any driver basis with a minimum age attached — commonly any driver over 19, 21, 25 or 30. Each band prices differently, and the right one is a commercial decision rather than a technical one: the question is what it costs you to be able to put anybody in any van at short notice.

  • Room to take on new work

    Winning a route or a contract usually means more vans and more drivers at short notice, and it is a poor moment to discover the policy cannot stretch. We would rather set the fleet up with headroom in the driver basis and the vehicle schedule from the start than renegotiate it in a hurry on the day you need it.

  • Seasonal peaks without a second policy

    Most courier operations are not the same size in November as in June. Short-term vehicle additions for the peak, temporary drivers and hired-in vans can generally be handled on the existing fleet rather than bolted on separately — which matters when the uplift lasts eight weeks and the paperwork has to happen in a day.

  • One renewal date, one set of paperwork

    Running six vans on six individual policies means six renewal dates, six proposal forms and six sets of documents to find when a customer asks for evidence of cover. A fleet collapses that into one — and one conversation a year in which the whole operation gets looked at properly.

  • Rated on your record, not each driver’s

    The real advantage of moving off individual policies. A fleet is rated on the operation’s own claims experience, so one driver’s speeding conviction or a new recruit’s thin licence history stops being a separate pricing event. Run it well and the whole fleet feels the benefit.

Telematics, cameras and risk management

On a courier fleet the claims record is the premium. Vehicles and postcodes set the starting point, but what decides the price over three or four years is how often the fleet has claims and what happens when it does. That is the part you can influence — and the part insurers will reward evidence on.

  • Telematics-rated fleet policies

    Some insurers will rate a courier fleet on recorded driving data rather than on the usual proxies of age and postcode alone. Units in the vans report speed, harsh braking, acceleration, cornering, idling and time of day, and the fleet is judged on how it is actually driven. For a well-run operation carrying a young driver or two, that can be the difference between a workable quote and a prohibitive one.

  • Forward-facing and in-cab cameras

    The most useful thing a camera does is settle liability. A courier van in heavy traffic attracts disputed claims and the occasional induced accident, and footage turns a fifty-fifty argument into a closed file. Insurers increasingly ask whether cameras are fitted and how long the footage is retained — a system nobody downloads from is worth very little.

  • Driver scoring and league tables

    Most telematics platforms produce a score per driver. The value is not the number, it is the conversation it makes possible — being able to see which three drivers generate most of the harsh braking, and deal with it, before it turns into claims. Insurers take a documented process here seriously because it is the one thing that changes future losses.

  • Licence checking and driver vetting

    Endorsements accumulate quietly, and a driver who picked up six points in March is a different risk by August. Checking licences at recruitment and at intervals afterwards — through the DVLA share code system or a checking service — is cheap, and it is among the first things an insurer asks about when a fleet’s losses are being discussed.

  • Written policies that actually exist

    Mobile phone use, daily walkaround checks, loading and load security, what a driver does at the scene of an accident, and what happens to the van overnight. None of it is complicated. What matters to an underwriter is that it is written down, that drivers have seen it, and that somebody notices when it is ignored.

  • What risk management realistically does

    It is worth being honest about this. Fitting telematics in October rarely produces a discount in November — insurers price on evidence, and evidence takes a renewal cycle or two to accumulate. What risk management does is change the direction of travel: a fleet with falling claims frequency and a story to tell is a fleet that markets will compete for.

Why choose Aldium as your courier fleet insurance broker?

Courier cover is not a product you buy off a comparison site — most of them will not quote hire and reward at all. It is arranged, which means understanding how the fleet runs, who drives it and where it works before going anywhere near an insurer, and then being contactable when something changes.

  • Independent, not tied to an insurer

    Hire and reward narrows the market, and a lot of what is left will not look past a postcode and a claims count. We are not owned by an insurer and not working to a panel we are obliged to use, so we can approach the markets that actually write courier fleets rather than the ones that happen to be on a list.

  • Built to flex, and quick about it

    A van bought on Friday needs to be earning on Monday. Vehicle additions, removals and swaps are routine work for us, done by someone who picks the phone up rather than through a portal that updates overnight — which on a courier fleet is most of what a broker is actually for.

  • Claims handled in-house

    We have our own claims manager. Courier claims are frequent and the urgency is always identical — the van needs to be back on the road and the customer needs an answer today. You ring us and we take it up with the insurer rather than joining a queue.

  • A named contact who knows the fleet

    The same people each year, who know the vehicle list, the driver basis and the history. No script, and nobody asking you to explain the operation again every twelve months.

  • Competitive across the UK

    We place fleets from the Highlands to the South Coast and everywhere in between, including inside the M25. Rural high-mileage work and dense city multi-drop are written by different appetites, and being independent means we can take a fleet to whichever one fits rather than accepting the first rating offered.

  • We get the goods in transit right too

    Most courier programmes come apart in the gap between the motor policy and the transit cover. We will ask what terms you carry under and what your heaviest and most valuable loads look like, so the two sit together properly rather than being bought from two places and hoped about.

What kinds of courier fleet do we insure?

“Courier” covers a lot of very different operations, and insurers rate them differently depending on what is carried, how far and how often. These are the ones we see most:

  • Same-day courier fleets

    Dedicated and time-critical work, often at short notice and over long distances.

  • Multi-drop parcel fleets

    High drop counts, frequent small claims and a loss ratio that needs managing.

  • Final-mile delivery contractors

    Working to a contracting principal with its own insurance requirements.

  • Owner-driver networks

    Fleets built on self-employed drivers, where status and cover both need checking.

  • Pallet network members

    Trunking and local delivery under network conditions of carriage.

  • Medical & pharmaceutical couriers

    Time and temperature critical loads, often high value for their weight.

  • Temperature-controlled fleets

    Chilled and frozen work, where a fridge failure is a total loss of load.

  • Document & legal couriers

    Low weight, high consequence, and small vehicles doing high mileage.

  • Furniture & white goods delivery

    Two-person crews, installation at the delivery point and damage on the threshold.

  • E-commerce fulfilment fleets

    Own-brand delivery operations running alongside a warehouse.

  • European & cross-channel couriers

    International legs and vehicles away from base for days at a time.

  • Mixed courier and haulage fleets

    Vans alongside 7.5 tonne and above on one schedule.

Not quite any of those? What moves a courier risk is the class of use, the radius and annual mileage, who is driving and where the vehicles sit overnight — not the name of the operation. If you have been declined elsewhere, or the renewal has jumped after a bad year, it is still worth a call.
Row of liveried courier vans parked at a depot ready for the morning run
Class of use, radius and who is driving move the premium more than the number of vans does.

Competitive wherever your routes run

We place courier fleets across the whole of the UK, and the two ends of the market look nothing like each other. A fleet working out of a yard in the Borders and a fleet working inside the North Circular present completely different risks — and they are not written by the same appetite. Being independent means we can go to both.

If your routes are rural or regional

  • Long distances between drops, so high annual mileage on relatively few vehicles.
  • Single-carriageway and unlit roads, where the claims that do happen tend to be more severe.
  • Vehicles usually kept at a yard or farm overnight, which helps on theft but raises questions about security and lighting.
  • Distance from an approved repairer, which lengthens downtime and makes replacement vehicle cover worth more than it looks.
  • Smaller driver pools, so an any-driver basis with a sensible minimum age often matters more than it would in a city.

If your routes are urban or central London

  • High drop density, so far more vehicle movements and manoeuvres per mile than any other kind of fleet.
  • Frequent low-value damage — kerbed wheels, wing mirrors, scrapes in loading bays — which drives claims frequency rather than cost.
  • Congestion charging, ULEZ and clean air zones shaping which vehicles you can realistically run.
  • Theft from vehicles at the drop, and overnight parking that is often on-street rather than in a compound.
  • A higher incidence of disputed and induced accidents, which is where camera footage earns its money.

Postcode is a factor, not a verdict. Some insurers will decline a central London courier fleet on the address alone and others will price it properly once they understand the operation; the same is true in reverse for very high-mileage rural work. We are not tied to one market, so rather than accepting the first rating we get, we put the fleet in front of insurers whose appetite actually fits where it works — which is usually where the difference at renewal comes from.
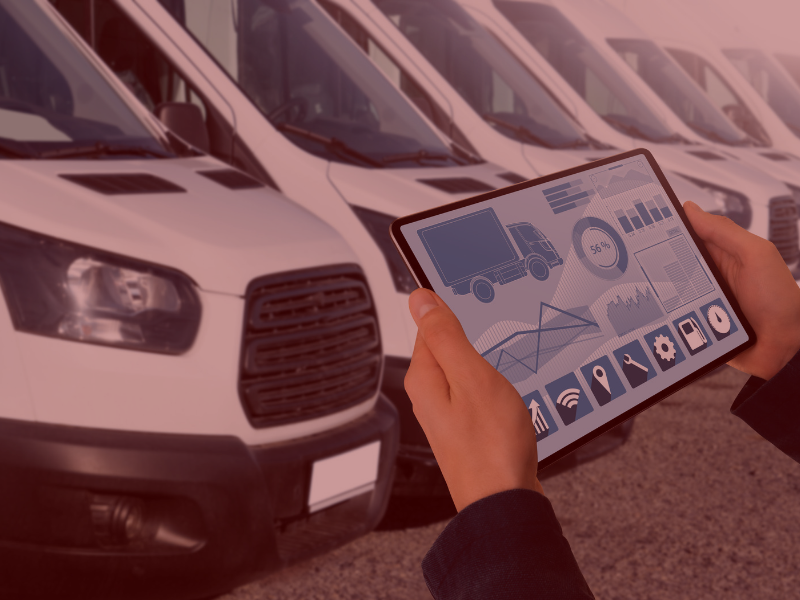
Fleet manager checking a vehicle schedule on a tablet beside a row of courier vans
Most of what decides a courier renewal is administrative, and all of it is fixable.

Six questions worth asking before your fleet renewal

None of these are about the small print. They are the things that separate two courier fleets running identical vans on identical work and paying very different premiums — and every one of them is settled long before anything goes wrong.

  • Is the class of use right on every single vehicle?

    Fleets drift. A van gets borrowed for an own-goods run, a director takes one home at weekends, a vehicle joins from another part of the group and nobody updates the use. Every vehicle doing courier work needs to be on hire and reward, and anything doing something else needs declaring. It is the cheapest thing on this list to fix and the most expensive to get wrong at the roadside.

  • What is the driver age band actually costing you?

    The gap between any driver over 19 and any driver over 25 can be substantial, and most fleets pick a band once and never revisit it. Both questions are worth asking at renewal: what would the cheaper band save, and what would it cost you in drivers you could no longer put in a van at short notice? On a fleet that has matured, the answer often changes.

  • How fast can you actually get a van on cover?

    Not in theory — in practice, at half past six on a Monday when a replacement has arrived and a route needs covering. Ask how mid-term additions are handled, whether cover can be confirmed verbally, and how quickly the vehicle hits the Motor Insurance Database. On a courier fleet this is worth more than a small difference in premium, and it is rarely what anyone compares on.

  • Would telematics change your terms — and could you live with it?

    Worth asking both halves. Some markets will only consider a courier fleet with younger drivers where there is telematics on it, so it can open doors rather than just shave pennies. But the data belongs to the conversation too: if the fleet is driven hard, a system that proves it is not automatically in your interest. Better to know before you fit it than after.

  • Is anybody checking the licences?

    On an any-driver fleet the insurer is relying on you to know who is driving. Points accumulate quietly, disqualifications happen, and agency drivers arrive with a history nobody has looked at. A documented check at recruitment and at intervals afterwards costs almost nothing, and it is one of the first things raised when a fleet’s losses come up for discussion.

  • Does your goods in transit limit match your heaviest load?

    The one non-motor item worth putting on this list. Work from the maximum value on any one vehicle at any one time, not the average job. Then check the basis: cover that follows your conditions of carriage pays what you are legally liable for, and under the RHA Conditions of Carriage 2020 that is capped at £1,300 per tonne of gross weight. All risks cover insures the goods instead. Both are legitimate — knowing which one you quoted the customer is the point.

General guidance for UK courier operators, not legal advice, not advice on your own circumstances, and not a statement of what any particular policy covers. The liability limit quoted is that in the RHA Conditions of Carriage 2020; whether those conditions apply to a given contract, and how, is a question for your own legal adviser. Driver age bands, telematics terms and mid-term adjustment arrangements vary between insurers. Your own policy wording and schedule decide whether a claim is paid. If you are unsure how yours is set up, we are happy to look at it with you.
How arranging your cover works

Four steps, and you can stop at any of them. Nothing is arranged and nothing is chargeable until you say so.

  • You get in touch

    Through the form on this page or on 0151 336 5881. We will want the basics: how many vehicles and what they are, what you carry, who drives, and roughly where you operate.

  • We build the submission

    Vehicle schedule, driver list and experience, annual mileage and radius, goods carried and the limits you need, overnight parking arrangements and your claims experience. On a courier fleet the claims record is the number that moves the price most.

  • We approach the market

    We go to insurers who write hire and reward and goods in transit, and present the fleet properly — including the telematics, the cameras and the driver vetting, which a generic submission has no way of showing.

  • You decide

    We set out what is covered, what is not, the conditions attaching to the goods in transit section and the price, in plain English. Nothing is bound until you tell us to go ahead.

What to have to hand. It speeds things up a great deal if you can find your current schedule and renewal notice, a vehicle list with registrations and values, a driver list with dates of birth and licence details, your claims experience for the last three to five years, and a copy of the conditions of carriage you trade under. If some of that is missing, ring anyway — we can work from what you have.

What do our clients say about working with us?

Don’t just take our word for it — here’s what businesses across the UK say about Aldium on Google.

Posted on Google Google
Sam Booth profile picture
Sam Booth
Google star 1Google star 2Google star 3Google star 4Google star 5Trustindex verifies that the original source of the review is Google.
Pleasure to work with - patient, competitive on price and helpful for quite an awkward insurance project. Much appreciated!
Posted on Google Google
Nicola Jackson profile picture
Nicola Jackson
Google star 1Google star 2Google star 3Google star 4Google star 5Trustindex verifies that the original source of the review is Google.
Posted on Google Google
Neil Lyon profile picture
Neil Lyon
Google star 1Google star 2Google star 3Google star 4Google star 5Trustindex verifies that the original source of the review is Google.
Easy to deal with, competitive price, very pleased with the service received
Posted on Google Google
Radu Gramada profile picture
Radu Gramada
Google star 1Google star 2Google star 3Google star 4Google star 5Trustindex verifies that the original source of the review is Google.
4th year with Aldium and getting better by the day. The team is always working in the background and the result are incredible. Really comprehensive and detailed explanations on why some insurers are better then other and quality advice offered along with multiple choices of cover. Every year we are getting more benefits and better prices. Would stronly recommend.
Posted on Google Google
Ron Jones profile picture
Ron Jones
Google star 1Google star 2Google star 3Google star 4Google star 5Trustindex verifies that the original source of the review is Google.
Renewal was done with no problems at all -quicky ,efficiently and professionally and to my liking
Posted on Google Google
Keith Lindsay profile picture
Keith Lindsay
Google star 1Google star 2Google star 3Google star 4Google star 5Trustindex verifies that the original source of the review is Google.
I have been very satisfied with the cover arranged for me and am impressed with the personal needs assessment and discussion of alternatives. Very pleasent experience, to which I will return.
Posted on Google Google
Donna Lawson profile picture
Donna Lawson
Google star 1Google star 2Google star 3Google star 4Google star 5Trustindex verifies that the original source of the review is Google.
Fabulous company and wonderful staff. Whatever we need in Insurance is explained so that we understand all.
Posted on Google Google
Mark Hughes profile picture
Mark Hughes
Google star 1Google star 2Google star 3Google star 4Google star 5Trustindex verifies that the original source of the review is Google.
Really thorough quote, covered thing are previous brokers had never discussed, very happy with the service.
Posted on Google Google
stewart bailey profile picture
stewart bailey
Google star 1Google star 2Google star 3Google star 4Google star 5Trustindex verifies that the original source of the review is Google.
Aldium have been a constant supplier for our vehicle insurances for a number of years. Nothing is ever too much trouble when replacing vehicles, or indeed when we just need a bit of advice regarding explanation of terms or such like. When policy renewal time comes around, they don't contact us until they've done their homework and have sourced the best value policy available for our needs, at the best possible price. Thank you to everybody at Aldium, we have no intention of looking elsewhere for our insurance provider.
Posted on Google Google
Paul Thompson profile picture
Paul Thompson
Google star 1Google star 2Google star 3Google star 4Google star 5Trustindex verifies that the original source of the review is Google.
Great customer service, highly recommended!
Verified by Trustindex
Trustindex verified that these reviews were published on Aldium Insurance Services Ltd's Google Business Profile. Learn more

How much does courier fleet insurance cost?

There is no standard price for courier fleet insurance in the UK. Premiums are worked out individually from the number and type of vehicles, the driver basis you choose, the mileage and radius, where the fleet is based and works, and — above all — your own claims experience. On multi-drop work the claims record matters more than the vehicles do, which is why two fleets running identical vans on identical routes can be quoted very differently.

What moves the price

  • Fleet size and vehicle types

    How many vehicles, what they are worth, and the mix of car-derived vans, 3.5 tonne Lutons and anything heavier sharing the schedule.

  • The driver basis you choose

    Any driver over 19, 21, 25 or 30, or a named schedule. This is one of the few levers you control directly, and the spread between the bands is wider than most operators assume.

  • Radius and annual mileage

    Local multi-drop, regional trunking or national same-day. Couriers cover enormous mileage, and exposure is largely a function of time on the road.

  • Where the fleet is based and works

    Postcode, the density of the routes and where the vehicles sit overnight. A compound, a depot yard and a driver’s street are three very different answers — and city and rural fleets are written by different appetites.

  • Telematics, cameras and risk management

    Whether the fleet is monitored, what the data shows, and whether there are documented licence checks and driver policies behind it.

  • Claims history

    Your own record over three to five years, looked at for frequency as much as cost. On multi-drop it is the single biggest factor in the price.

As independent brokers we search our panel of commercial motor insurers to find cover that balances protection, flexibility and price for how the fleet actually runs. Request a tailored quotation or call 0151 336 5881.

Courier fleet insurance FAQs

The questions courier operators ask us most often. If yours isn’t here, call us on 0151 336 5881 — a real person will pick up.

How many vehicles do I need for a courier fleet policy?

Most insurers will look at a fleet from three vehicles upwards and some will start at two. Below that you are generally looking at individual hire and reward policies.

The advantages of moving onto a fleet are practical as much as financial: one renewal date, vehicles on and off mid-term without a new policy each time, and rating based on your own claims experience rather than each driver’s individual history. On a growing operation it is usually worth having the conversation shortly before you get there rather than afterwards.

Can I add and remove vehicles during the policy year?

Yes, and on a courier fleet you will. Vehicle additions, removals, swaps and temporary hired-in vans are handled as mid-term adjustments — the premium is adjusted pro rata for the remaining period and the schedule is updated, rather than a new policy being set up.

What varies between brokers is how quickly it happens. Ask whether cover can be confirmed verbally or by email the same day, how fast the vehicle reaches the Motor Insurance Database, and whether there is an administration fee each time. On a fleet that changes every few weeks those details matter more over a year than a small difference in premium.

What are the driver age bands, and which should I pick?

Fleet policies are usually written on an any driver basis with a minimum age attached. The common bands are any driver over 19, 21, 25 or 30, and each prices differently — the lower the age, the wider the pool and the higher the premium. A named-driver schedule is an alternative where the team is settled, and is often cheaper again.

The right answer is a commercial one rather than a technical one. If you recruit at short notice, take agency drivers or train young drivers up, the flexibility of a lower band is usually worth paying for. If the same six people have driven for you for five years, it probably is not. It is worth re-testing at each renewal, because fleets mature and the answer changes.

Will telematics or cameras reduce my premium?

Nobody can honestly promise that, and we would be suspicious of a broker who did. What is true is that insurers take them into account, that some markets will only consider a courier fleet with younger drivers where telematics is fitted, and that camera footage settles liability disputes that would otherwise be shared or lost.

The effect usually shows up over a renewal cycle rather than immediately, because insurers price on evidence and evidence takes time to accumulate. A fleet that can show falling claims frequency, a documented licence-checking routine and a process for dealing with the drivers who score badly has far more options at renewal than one that cannot — and on a courier fleet options are what move the price.

Does the fleet policy cover the parcels in the back?

No. The motor policy insures the vehicle and your liability to other road users. The consignments need goods in transit cover, which is a separate policy sitting alongside the fleet.

Two things are worth checking on it. The limit should be based on the maximum value on any one vehicle at any one time rather than the average job; and the basis matters, because cover that follows your conditions of carriage pays what you are legally liable for rather than what the goods are worth. There is more on that in the section above.

Are you competitive if we operate in central London, or somewhere very rural?

Both, and they are different problems. A dense urban fleet generates a lot of low-value damage and attracts disputed claims, so some insurers decline the postcode outright while others will price it sensibly once they understand the operation. A rural fleet does enormous mileage on fast single-carriageway roads, which produces fewer but heavier claims, and not every market is comfortable with that either.

Because we are independent we are not stuck with whichever of those two appetites happens to be on a panel. We place courier fleets across the whole of the UK and go to the insurers whose appetite fits where the fleet actually works, which is usually where the difference at renewal comes from.

Can you cover a fleet with young drivers or a poor claims record?

Often, yes. Both narrow the field and both affect the terms, but neither closes the market on its own. Young drivers in particular are where telematics earns its place, because some insurers will look at a fleet with them on board and not otherwise.

What makes the difference is being able to show what has changed — cameras fitted, a driver vetting standard, licence checks in place, or simply a clean twelve months since the bad year. Be straight with us about the history from the start: under the duty of fair presentation, undisclosed losses are what an insurer will point at if a later claim is disputed.

Ready to get your courier fleet properly covered?

Whether your renewal is coming up, you are taking on a new contract with its own insurance requirements, or you are not certain what your goods in transit cover would actually pay out, challenge us to take a look. We’ll go through what you have now and show you what our panel of commercial motor and transit insurers can offer. No obligation, no call centres, just straight answers.

Aldium Insurance Services Ltd · Viscount House, High Street, Neston, CH64 9AD · Independent commercial insurance brokers for UK fleet and transport businesses.

Page last reviewed: